PeerBerry is one of Europe’s largest P2P lending marketplaces, founded in 2017 by Aventus Group. Investors fund consumer, business, leasing, and real-estate loans with a 60-day buyback guarantee, earning roughly 9–10% net in practice. Since January 2026, PeerBerry also offers a fee-free secondary market for early exits. It doesn’t hold a dedicated financial licence, but its track record — including full repayment of war-affected Ukrainian loans — is among the strongest in the sector.
What is PeerBerry?
Founded in 2017, PeerBerry is a European peer-to-peer investment platform launched by Aventus Group, one of Europe’s larger non-bank lending groups. The platform provides retail investors with access to debt investments originated within the Aventus ecosystem and its partner lenders, covering short-term consumer loans, long-term loans, leasing, business loans, and selected real-estate-backed exposures. The platform operates from Croatia, where it moved its operations from October 1, 2021, under the legal entity Peerberry d.o.o.
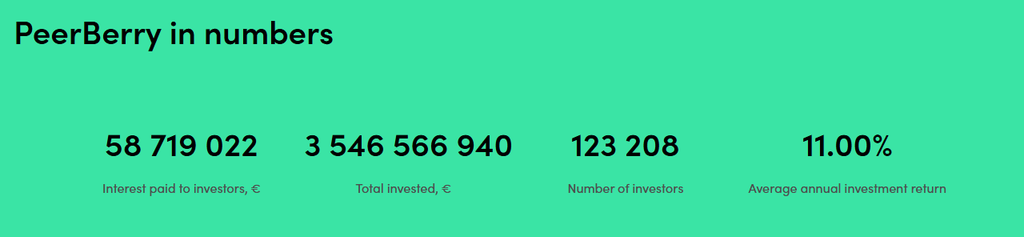
It has grown considerably since our last review. PeerBerry is now active with over 119,000 investors and more than €56M in paid interest, and €3.35 billion in total funded loans — up from roughly 87,000 investors and €2.7–3 billion in mid-2025.
What returns can you expect on PeerBerry in 2026?
PeerBerry currently advertises investor returns typically ranging around 10% to 11% annually, depending on loan type, duration, and market availability. These are nominal interest rates set at the loan level rather than guaranteed portfolio returns.
Real investor data is a useful reality check: across 296 PeerBerry portfolios tracked on P2P Dash, the median net return (XIRR) is 9.3%, with the middle 50% of investors earning between 8.2% and 10.2% (as of August 8, 2026). That’s slightly below the “average 11%” figure in our 2025 review — a reflection of lower interest rates across the market rather than any deterioration in the platform.
✅ Key Strengths
Secondary market — now live
This is the biggest change since our last review. On January 15, 2026, PeerBerry introduced a secondary market, allowing investments to be sold before the end of the loan term. No fees apply, only full investments can be sold, and investments can be sold at their remaining value or with a discount of up to 50%. It’s still new, so liquidity depth is worth watching — as it is new there is very little information on the liquidity in the secondary market yet.
Buyback and group guarantees
Loans are backed by a 60-day buyback guarantee and a group guarantee from the parent companies of the loan originators, giving investors two layers of protection if a borrower falls behind.
A proven stress test
PeerBerry’s handling of the war in Ukraine remains its strongest credential. Its December 2024 repayment of €51.4 million in Ukrainian war-affected loans — in full, with interest — closed that chapter entirely. Portfolio health has stayed clean since: the platform reported 0% of funds in recovery as of April 2026.
Mobile app and Auto Invest
PeerBerry provides a mobile app available on the Apple App Store and Google Play. Its Auto Invest tool allows investors to select individual lenders as well as borrower countries, loan terms, interest rates, investment amount, loan type or the buyback guarantee option, with a minimum investment per loan of EUR 10.
Fund segregation and transparency
Investor funds are held in a segregated bank account under Peerberry d.o.o., and the platform consistently publishes regular updates on its portfolio quality.
⚠️ Key Drawbacks
No dedicated financial licence
PeerBerry does not hold a financial license. Unlike ECSP-licensed platforms, it operates outside the EU crowdfunding regulatory framework — something more conservative investors will want to weigh.
Concentration in the Aventus ecosystem
Most loans come from companies connected to Aventus Group. Some investors see this as the main structural concern — one reviewer described the platform’s reliance on Aventus as a single point of failure, despite its clean track record.
Short-term, consumer-heavy loan book
Although PeerBerry lists several loan types, available opportunities were mostly short term, with most maturing at one month at the time of one recent review — meaning much of the exposure is to payday-style consumer lending.
Early secondary market
The new secondary market is a real improvement, but partial sales are not possible, and its liquidity hasn’t yet been tested under market stress.
🗣️ What are investors saying in 2026?
Community sentiment is broadly positive. PeerBerry holds a 4-star rating on Trustpilot based on 263 reviews. Cash drag, a common complaint in our 2025 review appears to have eased: one investor writing in August 2026 noted that past issues with a lack of investment opportunities had disappeared, at least for the time being.
On P2P Dash, of 126 stated strategies for PeerBerry, 55% plan to add funds or reinvest, 17% intend to hold, and 29% plan to reduce or exit, and in Q2 2026 PeerBerry ranked 6 of 46 platforms by net capital flow.
📊 Platform Comparison Snapshot
Feature PeerBerry Founded 2017 (Aventus Group) Headquarters Croatia (Peerberry d.o.o.) Investors 119,000+ Total funded €3.35 billion+ Advertised return ~10–11% Median real net return ~9.3% (P2P Dash, Aug 2026) Minimum investment €10 Fees to investor None Buyback guarantee Yes (60 days) + group guarantee Secondary market ✅ Yes, since Jan 2026 (no fees) Auto Invest ✅ Yes Mobile app ✅ iOS and Android Funds in recovery 0% (April 2026) Regulation ❌ No dedicated financial licence ✅ Who Should Consider PeerBerry?
- Investors seeking steady, moderate returns with a long, clean track record
- Beginners and small-scale investors, thanks to the €10 minimum, zero fees, and Auto Invest
- Investors who value buyback and group guarantee protection on short-term consumer loans
- Those who want more liquidity than before, now that the secondary market is live
🚫 Who Might Not Fit Well?
- Investors who require EU-regulated platforms (e.g., ECSP-licensed)
- Those wanting broad originator diversification beyond one lending group’s ecosystem
- Investors who need a deep, proven secondary market for guaranteed early exits
🔚 Final Verdict
PeerBerry has meaningfully strengthened its offering since 2025. The launch of a fee-free secondary market, a full mobile app, zero funds in recovery, and complete resolution of its Ukrainian loan exposure make it one of the most reliable consumer-lending marketplaces in Europe. Realistic net returns of around 9–10% are slightly lower than in previous years, but consistent.
The main trade-offs remain its lack of a dedicated financial licence and its concentration in the Aventus ecosystem. For most investors, PeerBerry works best as one solid building block in a diversified P2P portfolio — alongside products like Monefit SmartSaver and others covered in our platform comparison. Before investing, run it through our due diligence checklist.
Frequently asked questions
Is PeerBerry safe in 2026?PeerBerry has an eight-year track record, 0% of funds in recovery as of April 2026, and fully repaid its war-affected Ukrainian loans. However, it doesn’t hold a dedicated financial licence, and P2P investing always carries a risk of capital loss.
Does PeerBerry have a secondary market?Yes. Since January 15, 2026, investors can sell full investments before maturity, at face value or at a discount of up to 50%, with no fees.
What is the real return on PeerBerry?Advertised rates are around 10–11%, while the median net return tracked across real investor portfolios is about 9.3% as of August 2026.
Is PeerBerry regulated?No. PeerBerry operates through Peerberry d.o.o. in Croatia but doesn’t hold an ECSP or other dedicated financial licence. Investor funds are held in a segregated bank account.
Does PeerBerry have a mobile app?Yes, on both iOS and Android.
Capital at risk. Returns are not guaranteed. This review is for informational purposes and is not investment advice.
Discuss this article / 0 comments